…Ogun Govt links industrial expansion to investment, infrastructure, security
…Bank urges youths to embrace mortgage financing, says Nigeria needs 700,000 housing units annually
Toyyibat Qasim and Victorial Ikhedie
Gateway Mortgage Bank Limited has recorded a 12 per cent increase in profit after tax, rising from ₦179.08m in 2024 to ₦199.79m in the 2025 financial year, despite prevailing economic challenges in the country.
The bank also recorded growth in its total assets, which increased by 22 per cent from ₦11.09bn in 2024 to ₦13.52bn in 2025, while its loan portfolio expanded by 26 per cent to ₦5.77bn.
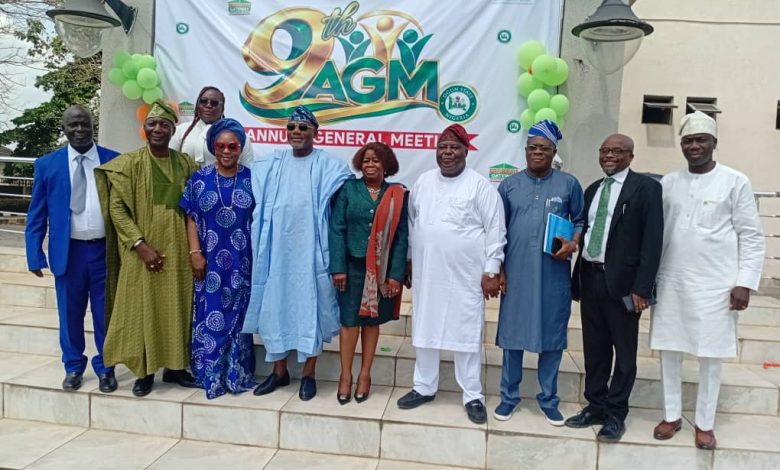
The financial performance was disclosed at the bank’s ninth Annual General Meeting held in Abeokuta, Ogun State, on Friday, where shareholders reviewed its audited financial statements for the year ended December 31, 2025.
Addressing shareholders, the Chairman of the Board of Directors, Samuel Durojaye, said the bank had sustained positive growth despite the difficult operating environment, attributing its performance partly to the support of the Ogun State Government, its ministries and agencies.
He said the bank had continued to support the state’s housing initiatives by providing mortgage facilities to beneficiaries of government housing projects.
A breakdown of the financial statements showed that profit before tax increased by approximately five per cent, from ₦271.25m in 2024 to ₦284.34m in 2025.
Interest income from loans rose by 28 per cent, from ₦756m to ₦969.48m, while income from investments increased by 63 per cent, from ₦689.36m to ₦1.13bn.
The bank’s deposit liabilities also grew by 36 per cent, from ₦3.69bn to ₦5.02bn, reflecting increased deposits during the financial year.
However, operating expenses increased by 32 per cent, from ₦1.12bn to ₦1.48bn, while the bank recorded an impairment allowance charge of ₦16.49m, compared with a reversal of ₦13.28m in the preceding year.
Speaking on the importance of mortgage financing to economic development, Durojaye said Nigeria needed to construct approximately 700,000 housing units annually over the next decade to bridge the country’s housing deficit.
He explained that mortgage institutions played a critical role in making home ownership accessible to individuals and supporting property developers to expand housing supply.
According to him, the availability of more housing units would help address the persistent rise in rents across major urban centres.
Durojaye also identified the difficulty of raising long-term funds as one of the major challenges confronting mortgage banks, explaining that the nature of mortgage financing required funding arrangements that matched the long repayment periods of housing loans.
“The minimum tenure for a mortgage is 10, 15 or 20 years. You cannot take people’s money when they expect it back in 90 days and put it into a property that will not pay back until 15 years,” he said.
He, however, urged Nigerians, particularly young workers, to embrace mortgage financing early rather than committing substantial portions of their earnings to annual rent payments.
“Instead of paying N2m in rent every year, why don’t you buy a house and start paying N200,000 monthly from your salary?” he asked.
He explained that prospective homeowners could acquire properties through mortgage arrangements and spread payments over an agreed period, thereby building long-term assets instead of continually spending on rent.